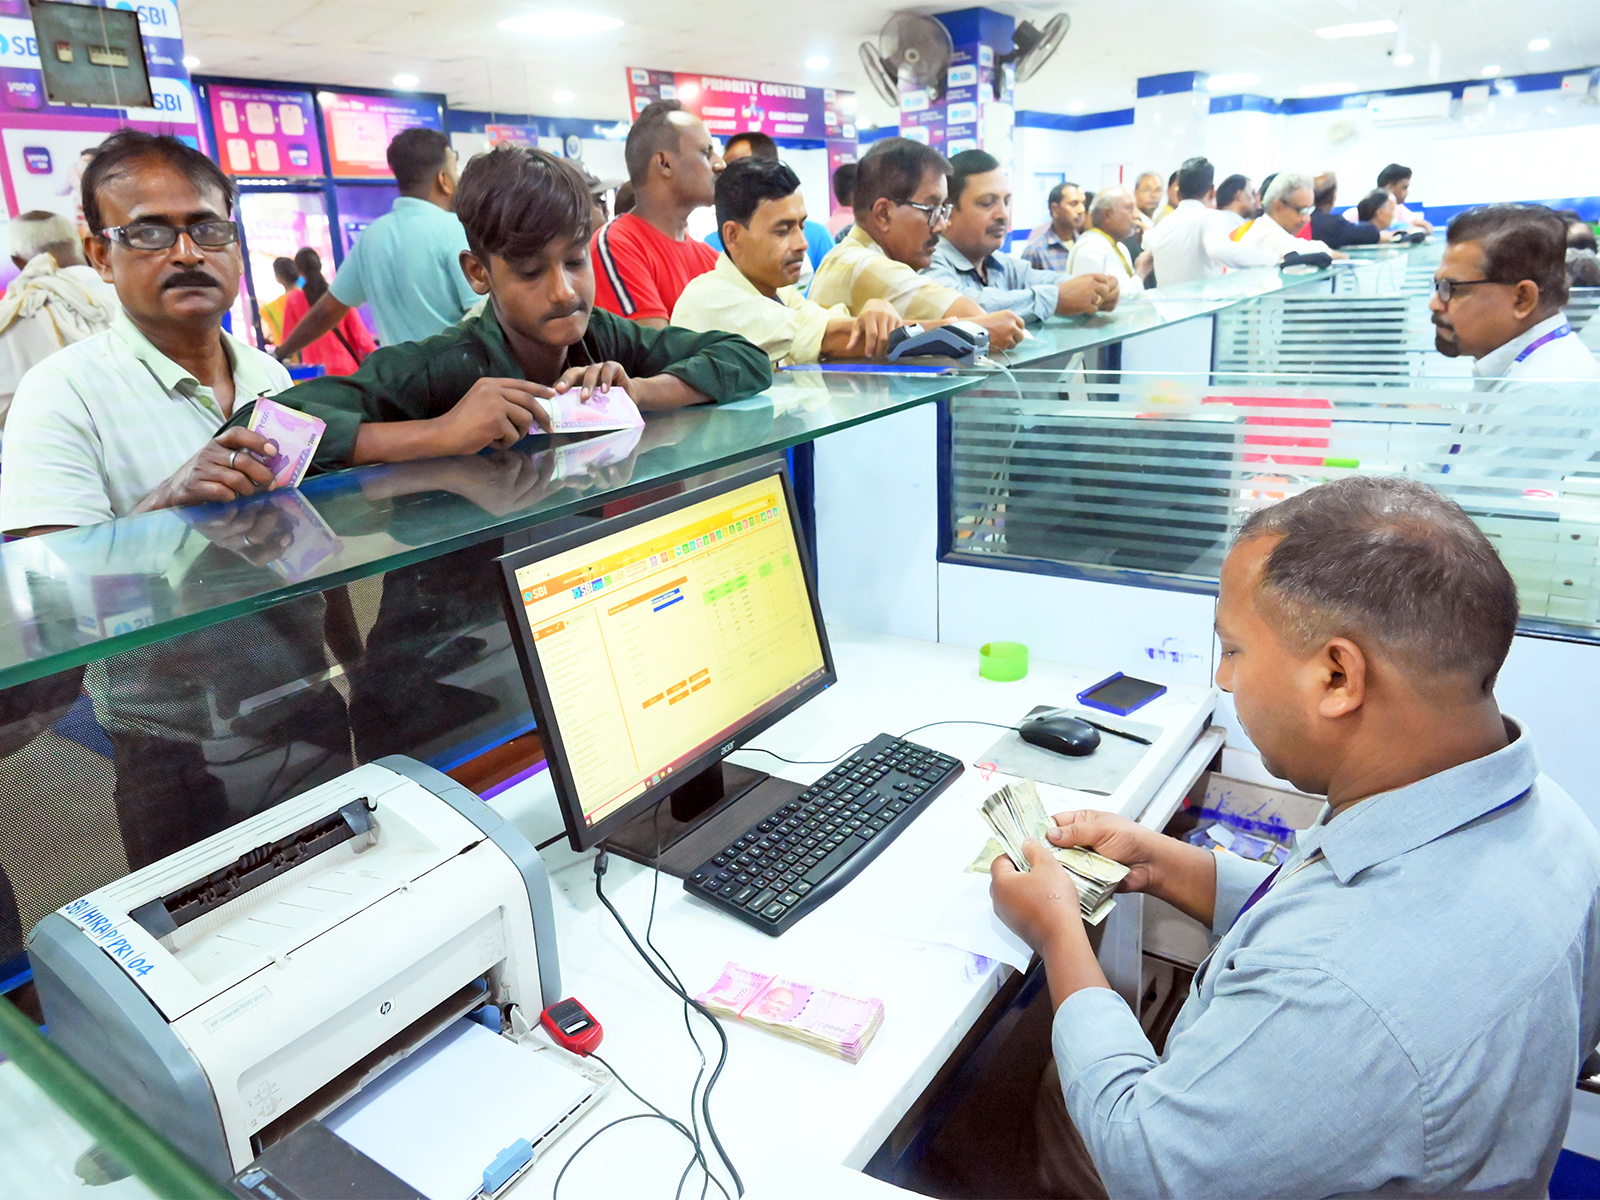
New Delhi [India], September 23 (ANI): India is entering a strong unsecured credit growth cycle, led by personal loans, supported by improving asset quality, stable household leverage, abundant system liquidity and a more risk-on approach from lenders, according to a report by UBS.
The report said the outlook comes after a three-year credit cycle across microfinance, personal loans, credit cards and unsecured business loans, with asset quality improving materially across most segments.
“We believe India is entering a strong unsecured credit growth cycle, led by personal loans,” UBS said in the report.
It added that the expected acceleration is being supported by healthy asset quality across banks and non-banking financial companies (NBFCs), flat unsecured household leverage over the past three years, ample liquidity in the financial system and lenders adopting a more risk-on stance.
The report noted that unsecured leverage in India rose from 6 per cent of GDP in FY19 to 10 per cent in FY24 but has since stabilised. At the same time, gold loans expanded sharply from around 1 per cent of GDP to about 5 per cent by FY26.
UBS expects growth in gold loans, which have acted as a key substitute for personal loans in recent years, to moderate as gold prices stabilise, potentially creating room for personal loan growth to pick up.
The early signs of this recovery are already visible. Citing CRIF data for August 2026, UBS said personal loan growth accelerated to around 30 per cent for NBFCs and 9 per cent for banks, with the latter marking a two-year high.
“Personal loan growth is beginning to accelerate for banks and NBFCs, at 9% YoY (the best in two years) and 30% YoY, respectively,” the report said.
The recovery in NBFC personal loans is being driven particularly by mid- and large-ticket loans, which together account for around 75 per cent of the overall book. The report showed total NBFC personal loan growth accelerating from 16 per cent year-on-year in March 2025 to 30 per cent in August 2026.
Asset quality has also strengthened. UBS said early delinquency trends across unsecured products were among the strongest seen in recent quarters, although pockets of stress remain in low-ticket business loans for NBFCs. Personal loan delinquencies in the 1-30 days past-due bucket for NBFCs declined to 1.8 per cent in August 2026 from 3.5 per cent in June 2024.
“Asset quality has improved materially across segments,” UBS said, adding that personal loan asset quality across ticket sizes for banks and NBFCs is at its strongest level in several quarters.
The report said the combination of improving asset quality, stronger personal loan growth and supportive liquidity could also improve the earnings outlook for select lenders, with UBS expecting the unsecured lending cycle to turn and personal loans to lead the next phase of growth. (ANI)
Related reading